Showing posts with label economic crash. Show all posts

Wednesday, December 23, 2009

 A nice overview of where things stand. Be sure to look through the stories listed and the comments. There's often better stuff there than even in the main post or stories.


Ilargi: For once, I'm afraid, I have to agree with Paul Krugman, himself a highly dysfunctional man in my eyes: the US government is Dangerously Dysfunctional. Only, Krugman, ever eager to be my anti-thesis, -somewhat comfortingly for me- rolls off the rails right away again by claiming that this is a result of party politics, and the blame lies squarely with the party he happens not to like, the GOP. And while I have little sympathy for that particular party, I do know that Krugman's portrayal is false.

Eliot Spitzer and Wiilam K. Black, seemingly honest and (therefore?) marginalized voices, ask to see emails concerning the AIG bailout(s). Therein, they contend, we’ll be able to see what really went on when the world's -then- largest insurer received $180 billion of your money, much of which was transferred at an amazing speed to the likes of Goldman Sachs. Make the emails public and we’ll know, because then "a thousand journalistic flowers can bloom". They actually wrote that.....

Yves Smith at Naked Capitalism reacts, and wants more. She thinks we should know why no research was done into all the parties involved, why they could receive money without being scrutinized before, during and after the bail-out process. Yves provides a well-written overview of Goldman Sachs actions that involved parts of the AIG funds. Still, calling for investigations into the matter, with or without emails, and more than a year after the fact, largely misses the crucial points here. Which takes us back to my buddy Krugman.

The AIG decisions were made in Washington. There was another party on the throne, but what difference did that make? The decision-making problems don’t vanish when another party comes to power. That much, we can all agree by now, has been made exceedingly obvious by the Bush to Obama transfer. The reason behind this is that the real rulers stayed in place while the White House changed occupants. The US simply isn't governed by its elected politicians. Or at least not by their ideas and convictions, if, when and where these differ from those of their donors.

If a politician can be elected only when (s)he has enough money (i.e. millions of dollars, and for a president hundreds of millions) to run a campaign, then the resulting policies will be dictated by those who donate that money. And since one dollar equals one vote, the grandma who ate mac and cheese for a week to donate $10 to Obama has no say, while a financial institution that gave $10 million does.

Both parties partake of the exact same largesse, so claiming that one is to blame and the other is not is nonsense. The system itself is broken. And you can't fix it with a bit more openness here or a few published emails there. You can only fix it by separating politics and business, by taking a big old axe and cruelly cutting clear through the umbilical chords so carefully and profitably attended to on K Street. Anything else is mere make believe. Nobody in Washington seeks the truth behind all this. Everybody seeks a story that makes them look good for their voters.

Arnold Kling describes it like this in The Harvard-Goldman Filter:
As to libertarians, certainly in a world with no deposit insurance or government guarantees I could argue against government interference in the structure of private banks. But banks are not private in this country. They are quasi-public institutions [..].

There is a synergy between big banks and big government. Jefferson and Jackson were right. So breaking up big banks fits in with breaking up big government. Which is why we won't see the Progressive elite breaking up big banks.


The trouble in Denmark on Capitol Hill runs much deeper than a vote or an idea. The country is governed by a few hundred enlightened souls who are all for sale, or they wouldn't be where they are. And if a soul does get lost on the Hill and tries to follow his or her conscience, the rest of them will drown it out.

This is not a new issue, though it has rapidly grown more poignant in the past 3 decades. What is new today is that the dysfunctional system has to deal with a crisis that cannot be dealt with as previous crises were: with more growth.

And without growth, what wealth there is has to be redivided, or society as a whole becomes untenable. And yes, redivided it is, but not in a way that would warrant society's continued viability. On the contrary, those who always had much will have more, while those who had least will now have nothing. And I’ve said it before, it's not a political statement to say that if a society doesn't provide a minimum for its poorest, that society must of necessity fail.

Read all the emails you want, investigate all the crooked deals made in the bail-outs. It won’t matter one iota. Once growth is gone, you need to prevent the rich from lobbying themselves into ever and even more riches. because these will have to come from the mouths of the desolate.

Or you can choose not to, but then your society is over and done with. Now, I don’t really think people will think I’m right. When most read that the noughties were the worst decade for stocks ever, as in since the 1820's, almost 200 years, they’ll think: well, it should go up then, shouldn't it?

Who among them concludes that growth may be gone, even if they know it can’t last forever? It was inevitable that they'd still be expecting -nay, even seeing- growth when the world around them is shrinking.


PS: The Financial Times headline "Bank of Japan says it will not tolerate deflation" inspired a good friend to come up with this quote about King Canute, about a millenium or so old. It would be a valuable lesson for many, not in the least the economists and assorted financial types who overestimate governmental powers and good will of many sorts and stripes.
"Henry of Huntingdon, the 12th-century chronicler, tells how Cnut set his throne by the sea shore and commanded the tide to halt and not wet his feet and robes; but the tide failed to stop.

According to Henry, Cnut leapt backwards and said "Let all men know how empty and worthless is the power of kings, for there is none worthy of the name, but He whom heaven, earth, and sea obey by eternal laws." He then hung his gold crown on a crucifix, and never wore it again."

Friday, October 3, 2008

Of Crashes, Failures and Bailouts - Round III

Should the Senate pass its revised version of the $700 billion bailout bill?

Yes - No
35% - 65%


FIGHT BACK.
CALL YOUR REPRESENTATIVES.
REJECT THIS ATTEMPT TO USURP YOUR POWER AND MONEY.

Representative Sherman's remarks on the House floor at 8:07 PM EST, Thursday, Oct. 2nd:

The only way they can pass this bill is by creating and maintaining a panic atmosphere. That atmosphere is not justified. Many of us were told in private conversations that if we voted against this bill on Monday... the markets would fall 2 or 3,000 points the first day, another couple thousand the second day, and a few members were even told that there would be Martial Law in America if we voted no.
This is what is driving the debate, the vote: Fear. It is what we have seen for the last 7+ years. Are you not tired of the lies?

UPDATE: Rep. Sherman also spoke again at 8:23 AM Friday morning. He points out again the pork and the fact the "oversight" is B.S.: the Congress has no power to enforce. He says again: let's stay here a week and develop a GOOD bill.

Let's review:

Claim by Paulson, Bernanke, Bush, McCain, et a.: The economy is fundamentally strong. Paulson: It's contained.

Reality: Obviously false.

---------------------------------------------------------------------

Claim: Paulson, Bernanke, Bush, et al.: We must act now. We don't have weeks. There will be financial disaster and Martial Law.

Reality: Obviously false.
  1. It's been more than a week.
  2. Secret conference call assures Wall Street first funds won't be used for a couple weeks while they decide who lives and who dies. Also, provisions have no teeth; all 700 billion will be available immediately.
Here's some more on that secret conference call. (Hat tip to Leanan at The Oil Drum.):

Financial Eugenics: The Paulson Plan for Survivor Bias

As I write this... I suspect that Congress will force the passage of the bill in some form because the media and political narrative on the necessity of the measure is unremitting and so horribly biased.

No alternatives will be considered.

No constraints on the unilateral executive authority of Hank Paulson will be considered.

No assurances that funds will be used to unlock credit markets or promote lending to the real economy (as opposed to the financial robber barons) will be considered.

...Having listened to all 42 minutes of the late night Treasury briefing of investment banks on Sunday, there is no doubt in my mind that this legislation represents the sort of federal largesse for Goldman Sachs, Morgan Stanley, Citibank and JPMorgan Chase that the Iraq war provided for Halliburton and Blackwater.

The most cynical moment in the call is when the Treasury official confirms, ”our preference would be to help the healthy banks become even healthier” rather than helping troubled banks or illiquid banks.

America is now a centrally planned economy where the Treasury will determine which firms survive and prosper...

Clearly what is going on here has nothing to do with kick starting the credit markets or stabilising the equity markets or restoring depositor confidence in banks. (Treasury official: “No provision in the legislation that mandates re-lending.”) What is going on here is a blatant attempt to provide government funds to a select cadre of firms (not all banks) which are chosen to be the survivors feasting off the carcasses of their less fortunate and less well-connected brethren as the downturn intensifies in the years to come.

The crash in equities will still happen. The debt deflation of the economy leading to mass commercial and consumer credit defaults will still happen. The collapse of many national, regional and local financial institutions will still happen. The bankruptcy of many municipalities and shortfalls in state budgets will still happen.

This bill is about engineering survivor bias to friends of the Bush administration... and unconditional authority of the Secretary of the Treasury.

...The SEC will support the plan and survivor bias by relaxing FASB 157 on mark to market accounting...

The Federal Reserve will support the plan by relaxing the definition of “control stake” in US banks and bank holding companies to allow secretive cabals to hold through private equity and offshore hedge funds... Many foreign creditors are irate at the losses... and this plan provides a secret way to buy them off and keep them lending and investing...

I would like to believe Americans expressed the courage to change over last weekend when they 25 to 1 rejected an unconstrained and unconditional bailout of Wall Street in favour of cold turkey deleveraging of the economy. I wish I could believe that it mattered in the political calculus, but the result of the House vote on the bill will tell us that.

Fight the survivor bias. It’s not your survival they’re engineering.
--------------------------------------------------------------------------------------------------

Claim: $700 billion will save us.

Reality: The Fed, a.k.a. Helicopter Ben, put over 60o billion in play and it did... nothing.

---------------------------------------------------------------------------------------------------

Claim: This will save Main Street.

Reality: Obviously false. There are mortgage resets coming for the next two or three years. That means this problem will just grind on and on... and this bill does NOTHING about that.

In fact, foreign investors get relief. I stated earlier this is inappropriate. It is likely unconstitutional. And why threaten veto if the provision is taken out? How can it possibly be of urgent interest to Americans? Sure, the world economy is important,but the ENTIRE WORLD is going to implode if this isn't passed this week? I've got a bridge to sell ya...


And who's buying banks and insurance companies? B of A, Goldman Sachs, JP Morgan... etc.... all buying, not selling. Buying assets and leaving liabilities... to YOU:


AIG to sell as many assets as needed to pay bailout

As Big Banks Converge...
Citigroup Inc.'s decision this week to gobble up most of ailing Wachovia Corp. is the latest in a string of blockbuster acquisitions that have transformed the banking landscape. A huge chunk of consumer deposits are now consolidated in three banking behemoths -- Citigroup, Bank of America Corp. and J.P. Morgan Chase & Co. -- not known for wooing consumers with high interest rates and low fees.

Wells Fargo to acquire Wachovia for $15.1 billion in all-stock deal, ends Citigroup talks


---------------------------------------------------------------------------------------------------

Claim: Not acting will cause a recession.

Reality: We have been in recession since the last quarter 2007 according to some, and virtually never got past the recession of 2001 according to others. The people saying we are not in a recession are in the government or neo-con pundits.

Chart of Growth in U.S.Gross Domestic Product (GDP)

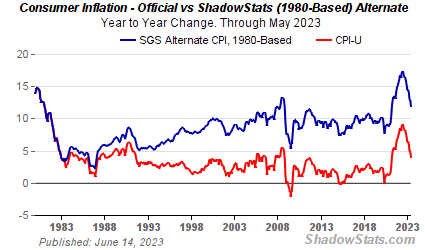
Inflation?
Chart of U.S. Consumer Inflation (CPI)

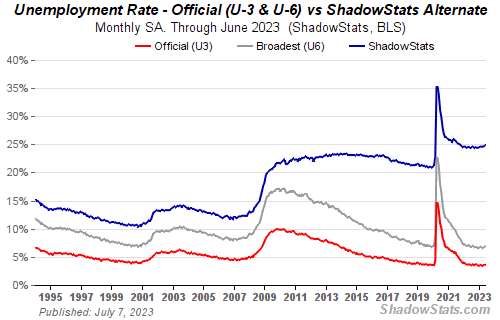
Unemployment?
Chart of U.S. Unemployment

And guess when the money supply started drying up. Last week? No.... Check out M3, which Bush stopped reporting in 2006 because it was "too expensive" to report and not important:

Chart of U.S. Money Supply Growth


FIGHT BACK.
CALL YOUR REPRESENTATIVES.
REJECT THIS ATTEMPT TO USURP YOUR POWER AND MONEY.

Ex-Treasury secretary O'Neill says Bailout Plan 'crazy,' 'lunacy'
Former U.S. Treasury Secretary Paul O'Neill said the $700 billion bank-rescue proposal under negotiation in Washington is "crazy," with potentially "awful" consequences for the world's largest economy.

"Doesn't this seem like lunacy to you?" said O'Neill, who was President George W. Bush's first Treasury chief, from 2001 to 2002, in a telephone interview Wednesday. "The consequences of it are unbelievably bad in terms of public intrusion into the private sector."

O'Neill's objections mirror those of Republicans in the House of Representatives who rejected the plan in a Sept. 29 vote. The former Treasury chief said he lobbied for an alternative solution that would offer guarantees for troubled assets, stopping short of purchasing the debt.

"Is anybody thinking there?" asked O'Neill, who also served as deputy budget director in the Ford administration. "It's too late, it's not going to make any difference and it's aggravating as hell when there's a better idea and you can't even get it in play," he said.

O'Neill, 72, was fired after an almost two-year tenure marked by strains with White House officials and comments that roiled markets.
Peter Schiff and Bob O'Brien on Glenn Beck: Causes and What the Future Holds

Great comments at:
3:10: GDP top drop 10% ~ 15% over next 12 ~ 15 months (Beck)
7:40: Govt' made it easy to borrow instead of work hard (Schiff)
8:09: - Gov't atfault - For years gov't kept things artificially supported... money supply... stopped working a few months ago... now engineering price of money...gov't actions pernicious, untested (O'Brien)


This is from an e-mail I got from Democrats.com:

The Senate's 74-25 vote for Paulson's Plunder came as no surprise, since the Senate is run by and for millionaires. So now it's back to the House of Representatives, where we shocked those millionaires on Monday by defeating their bailout bill by 228-205.

A terrified army of corporate lobbyists is working around the clock to switch 13 votes, but only 7 have switched so far - Jim Ramstad (R-MN), John Shadegg (R-AZ), Zach Wamp (R-TN), Ileana Ros-Lehtinen (R-FL), Shelley Berkley (D-NV), Emanuel Cleaver (D-MO) and John Lewis (D- GA). Other possible switches include Pat Tiberi (R-OH), Pete Hoekstra (R-MI), John Yarmouth (D-KY), Brian Bilbray (R-CA), Steve Rothman (D-NJ), Lee Terry (R-NE), Jim Gerlach (R-PA), Tim Murphy (R-PA), Jason Altmire (D-PA), and Gabrielle Giffords (D-AZ). But others may switch from Yes to No, including Ed Markey (D-MA), Charlie Melancon (D-LA), and Spencer Bachus (R-AL).

Bush's first Treasury Secretary, Paul O'Neill, called Paulson's plan "crazy" and "lunacy" with potentially "awful" consequences for the world's largest economy. Many of the best economists agree with O'Neill. Paulson's strongest supporters - including panicked CNBC hosts - now admit it will not raise stock prices or boost the economy as it falls into recession. Then why on earth should we give $700 $850 billion of our tax dollars to Wall Street??? Joe Lieberman gave away the real game when he told FOX " it will be good for John McCain."

With so much at stake, Congress should stay in session for another week (or two) to pass a much better (and cheaper!) plan proposed by Pete DeFazio (D-OR). But Congress desperately wants to go home so Friday may be our last chance to stop this $850 billion disaster .

(1) Call your Representative today!
First check how your Representative voted on Monday (and note switches above):
http://clerk.house.gov/evs/2008/roll674.xml
If (s)he voted NO, say "Thank you for helping stop the Bailout on Monday. Don't betray us now by voting YES on Friday, or I will vote NO against you on Election Day."
If (s)he voted YES, say "I'm outraged that you supported the Bailout on Monday, and I will remember on Election Day. If you want my vote on Election Day, you must vote NO on Friday."

(2) Join or organize a street protest against the bailout:
http://bailoutmainstreet.com/

FIGHT BACK.
CALL YOUR REPRESENTATIVES.
REJECT THIS ATTEMPT TO USURP YOUR POWER AND MONEY.